Syria Foreign Trade Statistics: Exports, Imports and Partners, 2010–2025

Syria’s foreign trade statistics show a sharp post-2011 collapse: exports fell from about US$11.3 billion in 2010 to roughly US$1 billion in 2021, with partial recovery to an estimated US$2 billion in 2025. Imports also shrank from US$17.5 billion in 2010 to about US$5 billion. The EU, China, Lebanon and Turkey are among its main partners.

Syria’s foreign trade at a glance

Syria’s recorded merchandise trade rests on two layers of data. Official figures begin with customs declarations, compiled by the Central Bureau of Statistics (Syria), المكتب المركزي للإحصاء في سوريا. They cover the areas where the government collected records in a given year. International datasets standardise those submissions into US dollars and add partner-country reports. The clearest annual reference points are 2010, the last year before the 2011 conflict, and 2021. A 2025 estimate indicates partial export recovery, but reporting remains uneven.

Latest available data

As of 2025, the most recent EU figures come from Eurostat. Global aggregates from UN Comtrade and ITC Trade Map continue to be revised as countries submit corrections. Many annual values between 2012 and 2020 are discontinuous and should be treated as lower-bound estimates.

Exports, imports and trade balance, 2010–2025

The table shows the annual series available from the sources consulted. Values are expressed in current US dollars and rounded to one decimal place. Years marked as estimates draw mainly on partner-country mirror records rather than on Syrian customs declarations.

YearExports (US$ billion)Imports (US$ billion)Trade balance (US$ billion)Source / note
201011.317.5−6.2UN Comtrade / ITC Trade Map
20118.516.0−7.5UN Comtrade / ITC Trade Map; final pre-conflict year
20124.010.5−6.5UN Comtrade / ITC Trade Map; reporting becomes partial
20132.58.0−5.5UN Comtrade / ITC Trade Map; mirror records gain weight
20142.07.5−5.5UN Comtrade / ITC Trade Map
20151.86.5−4.7UN Comtrade / ITC Trade Map
20161.55.8−4.3UN Comtrade / ITC Trade Map
20171.45.5−4.1UN Comtrade / ITC Trade Map
20181.35.2−3.9UN Comtrade / ITC Trade Map
20191.25.0−3.8UN Comtrade / ITC Trade Map
20201.14.8−3.7UN Comtrade / ITC Trade Map
20211.05.0−4.0UN Comtrade / ITC Trade Map; latest full annual
2022est. 1.2est. 5.5est. −4.3UN / ITC estimate; confirmation pending
2023est. 1.5est. 6.0est. −4.5UN / ITC estimate
2024est. 1.8est. 6.2est. −4.4UN / ITC estimate
2025est. 2.0est. 6.5est. −4.5UN / ITC estimate

In 2010 Syria exported about US$11.3 billion and imported US$17.5 billion, giving a trade deficit of US$6.2 billion. By 2021 exports had fallen by roughly nine-tenths to about US$1 billion, while imports dropped by about seven-tenths to about US$5 billion. The 2025 export estimate of about US$2 billion marks a partial recovery, but remains far below the 2010 level. The persistent gap after 2011 reflects both the collapse in export capacity and continued dependence on imported food, fuel and machinery.

Figures for Syria are less precise than for many other countries because official reporting has been incomplete since 2011. Between 2012 and 2020, annual series are discontinuous in Syrian official records. The UN and ITC fill gaps mainly from partner-country returns, which may differ from Syrian declarations. For that reason values after 2011 are best read as ranges rather than exact totals. A 2025 figure should be treated as provisional until the underlying customs and mirror records are confirmed.

What Syria exports and imports

ITC Trade Map classifies Syria’s recorded trade into broad product groups. On the export side, the groups most commonly reported are crude oil and petroleum products, phosphates and related chemicals, food products such as olive oil, fruit, vegetables, cumin and lentils, textiles and basic manufactures. Imports are more varied: refined fuels, cereals and processed foods, pharmaceuticals, machinery and electrical equipment, and vehicles and parts all appear in the data.

The mix is not stable from year to year. Crude oil and phosphate exports depend on security around production and transport routes, while food and textile exports respond to agricultural seasons and regional demand. Import priorities shift with the exchange rate and with availability of foreign currency.

Because Syrian official data are incomplete after 2011, the product groups are best read as relative indicators rather than exact shares. The same caveat applies to the EU product list: Eurostat records EU imports from Syria by product section, but the composition differs from the global totals reported by the UN.

Syria’s main trade partners

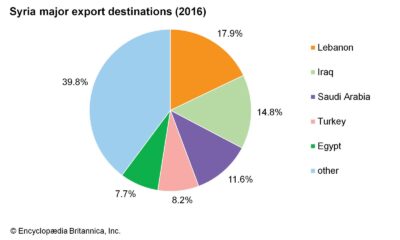
The partner mix shifts by year, but several names recur in the available datasets. According to Eurostat, total EU-Syria trade in goods reached €193 million in 2025, with EU imports from Syria at €150 million. Those Eurostat values cover the European Union as a bloc and are expressed in current euros, so they are not directly comparable with the US dollar totals in the annual table. UN Comtrade and ITC Trade Map partner rankings also point to China, Lebanon, Turkey, Iraq and Egypt as frequent counterparties in Syria’s recorded trade.

The partner table summarises the most recent available indications, with the EU as the only partner for which the sources consulted provide an explicit 2025 figure.

PartnerLatest reported indicationReported year
European UnionTotal trade with Syria €193 million; EU imports from Syria €150 million (Eurostat)2025
ChinaRecurrent top partner in Syria’s total trade recordsLatest reported year, variable
TurkeyRecurrent top partner, especially in import flowsLatest reported year, variable
LebanonMain regional transit and trade partnerLatest reported year, variable
IraqRegular partner in Syrian export and import recordsLatest reported year, variable
EgyptRegular partner in Syrian trade recordsLatest reported year, variable

Lebanon is particularly important as a transit route for goods that enter or leave Syria through the Mediterranean, while Turkey and Iraq account for substantial land-border trade. China appears mainly as a supplier of manufactured goods, and Egypt as a regional market for Syrian agricultural and industrial exports. The EU’s Generalised Scheme of Preferences (GSP) grants reduced duties on certain Syrian products, but its utilisation rate varies by product section and by year.

How to read Syria’s trade figures

Syrian official trade returns cover only the areas where the government could collect customs declarations. For the rest of the country, UN Comtrade and ITC Trade Map combine data reported by partner countries, which is why 2010 values are firmer than later ones. The UN converts trade values to US dollars using official exchange rates or partner-market rates, so small differences between datasets are normal.

World Bank WITS pulls together many of the same series and adds macro indicators, making it useful for comparisons with GDP. Before using a figure, check the year, the coverage note and the source. More detail on the statistical office behind Syria’s official records appears in an explainer on what the Central Bureau of Statistics covers.

Background: why the numbers shifted after 2010

Between 2010 and 2021 Syria’s recorded exports fell by roughly nine-tenths and imports by about seven-tenths. The contraction came with conflict, international sanctions and reduced activity at the ports of Latakia and Tartous. A weaker Syrian pound, examined in Syria’s currency crisis, and falling labour productivity reinforced the decline.

Frequently asked questions

What is Syria’s trade balance?

Syria has run a persistent trade deficit since 2011. Imports exceeded exports in every year for which comparable figures are available, although both flows collapsed after 2010.

What does Syria mainly export?

Crude oil, phosphates, food products, textiles and some manufactured goods. The exact mix varies by year and by the source that reports the data.

Who are Syria’s main trading partners?

The EU, China, Lebanon, Turkey, Iraq and Egypt appear most often in the available datasets, although rankings vary by year.

Where can I find Syria foreign trade statistics?

UN Comtrade, ITC Trade Map, Eurostat and World Bank WITS publish the underlying annual figures, including the 2010–2025 reference points.

Sources

UN Comtrade ITC Trade Map Eurostat World Bank WITS
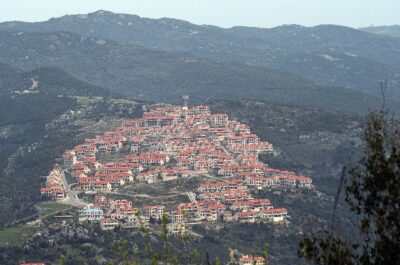
Al-Kafroun (Arabic الكفرون)

2004 Syrian Census: Syria’s Last Full Population Count

The 2004 Syrian census, conducted in September 2004 by the Central Bureau of Statistics, counted 17,920,844 people across Syria’s 14 governorates. It was the country’s last full population census; the next one planned for 2014 did not take place. The main dataset is available through the IHSN World Bank microdata catalogue and GHDx.

What was Syria’s population in the 2004 census?

Syria’s population at the 2004 census was 17,920,844, according to the General Census of Population and Housing 2004 carried out by the Central Bureau of Statistics (Syria) in September 2004. The figure is the official national total and remains the baseline for later population estimates. The count covered all 14 governorates of the Syrian Arab Republic and was published with demographic and housing indicators. It remains the last full population count, which is why researchers continue to cite the 2004 total when verifying older official figures. Because it was the last complete enumeration, the 2004 total remains the point of reference for population denominators in later demographic work.

How the 2004 count compares with 1994

The 2004 total of 17,920,844 represented a 30.02% increase over the previous census, held in 1994. The 1994 national total was about 13.78 million, equivalent to 13,783,144 people when calculated from the official 2004 figure and the 30.02% change. That increase added roughly 4.14 million people in ten years. Between the two censuses, Syria’s population grew at an average annual rate of about 2.7%. The 2004 round was the fifth in the census series that began in 1960; the 1994 round was the fourth.

Census yearNational populationChange from previous census
199413,783,144—
200417,920,844+30.02% (+4,137,700)

The 14 governorates covered by the census

The 2004 census enumerated all 14 governorates of the Syrian Arab Republic as they were defined at the time. The list runs from Aleppo in the north to Quneitra in the south-west and includes both rural and urban governorates. The same 14 governorates were the primary reporting units for the census tables and for later statistical yearbooks.

GovernorateCovered in 2004 census
AleppoYes
Rif DimashqYes
DamascusYes
HomsYes
HamaYes
HasakahYes
IdlibYes
Deir ez-ZorYes
LatakiaYes
DaraaYes
RaqqaYes
TartusYes
SuweidaYes
QuneitraYes

What the census measured

The 2004 General Census of Population and Housing collected information beyond the total population count. The IHSN/World Bank catalogue record for study SYR_2004_PHC_v01_M lists the following thematic areas:

  • households
  • housing materials
  • water supply
  • education
  • disabilities
  • deaths in the household
  • summary birth history

Labour force indicators were also part of the census output and informed later work on Syria’s labour force statistics. The listed topics cover household composition, housing conditions, water supply, education, disability, mortality and fertility, which are the main dimensions documented by the study metadata.

Where to consult the 2004 census dataset

The main catalogue records are the IHSN/World Bank Microdata Library and the Global Health Data Exchange. Study SYR_2004_PHC_v01_M is listed at https://microdata.worldbank.org/ ; the GHDx record titled “Syria Census 2004” is available at https://ghdx.healthdata.org/ and was last updated on 27 April 2026. Microdata access generally requires registration on the hosting platform. Both catalogue records document the study’s producers, sponsors and technical documentation. Researchers looking for the original census tables can consult the Central Bureau of Statistics publications, but the main digital access points for the microdata are the two catalogues named here.

Syria’s census history: why 2004 remains the benchmark

Syria held national censuses in 1960, 1970, 1981, 1994 and 2004. The 2004 round is the most recent full census. A further census planned for 2014 did not take place, leaving 2004 as the benchmark for official population figures. Post-2011 population figures used by the UN and other organisations are estimates, not census counts, and depend on methodologies and territorial control that differ from the 2004 enumeration. The census count does not measure displacement or refugees, which became central to statistical work only after 2011. Earlier censuses followed the administrative divisions current at each date; the 2004 total therefore reflects the population within the 14 governorates in force in that year. The resulting baseline still anchors work on Syria’s post-census economic and social crisis, and personal accounts such as a 113-year-old refugee’s memories of Syria before the 2011 conflict.

Frequently asked questions

When was the 2004 Syrian census conducted?

In September 2004.

What was the population of Syria in 2004?

17,920,844 people, according to the Central Bureau of Statistics.

How many governorates did Syria have in the 2004 census?

14 governorates, from Aleppo to Quneitra.

Was there a census in Syria after 2004?

No; the census planned for 2014 did not take place.

Who conducted the 2004 Syrian census?

The Central Bureau of Statistics (Syria).

Sources

  • Central Bureau of Statistics (Syria), General Census of Population and Housing 2004.
  • IHSN/World Bank Microdata Library, study SYR_2004_PHC_v01_M.
  • GHDx (IHME), Syria Census 2004.

Syria Population Indicators 2009: What Chapter 2 of the Yearbook Shows

The 2009 Syrian Statistical Yearbook’s Chapter 2, “Population and Demographic Indicators”, sets out Syria population indicators 2009: official population estimates, natural increase, fertility and mortality indicators, and governorate-level data through 2009. The Central Bureau of Statistics (Syria) published it. These pre-2011 figures should be paired with UN estimates for later years. The chapter itself serves as the reference point for verifying citations rather than a reproduction of its contents.

What Chapter 2 Covers

The chapter titled “Population and Demographic Indicators” in the Syrian Statistical Yearbook 2009 summarises the Central Bureau of Statistics’ population data up to that year. It brings together population estimates, natural increase, crude birth rate, crude death rate, total fertility rate, age-sex distribution, and governorate-level tables. The coverage is national, organised by governorate rather than by district. Official figures reflect administrative records, sample surveys, and the 2004 census base. Researchers citing a figure should check the chapter’s table and methodology notes before quoting it.

Population and Growth Indicators, 2000–2009

The chapter reports Syria population growth 2009 official figures for 2000 to 2009. The table below summarises what each indicator measures and how it is expressed, using the chapter’s definitions rather than reproduced values. “Coverage note” indicates the limits of the official series.

IndicatorWhat it measuresHow expressedCoverage note
Total population estimateResident population at mid-year, excluding Syrians abroad long-termNumber of personsNational and governorate-level; years under government control through 2009
Natural increaseBirths minus deaths over a yearNumber and rate per 1,000Based on registered events; may undercount unregistered births and deaths
Crude birth rateLive births per 1,000 residents in a yearRate per 1,000 populationOfficial registration areas only
Crude death rateDeaths per 1,000 residents in a yearRate per 1,000 populationSame registration limits as the birth rate
Total fertility rateAverage number of children per woman if current rates heldChildren per womanModel-based estimate from survey data
Age-sex distributionPopulation shares by age group and sexPercentage and population pyramidGovernorate and national level; 2004 census age structure as base

What the table does not cover

The official series stops where administrative reporting stops. The indicators do not cover internally displaced persons, refugees abroad, or areas outside government control during 2000–2009. They also do not estimate the effects of the conflict that followed 2011. A figure from Chapter 2 is therefore an official pre-2011 record, not a description of Syria’s current population. Post-2011 changes require UN estimates instead.

Chronology of Official Population Data, 2000–2009

  • 2004: Syria holds its General Census of Population and Housing; the count becomes the base for later estimates and projections.
  • 2005–2008: Statistical abstracts update population indicators annually, adjusting estimates to the 2004 census base.
  • 2009: The Statistical Abstract 2009 includes Chapter 2, “Population and Demographic Indicators”, summarising the official series through that year.

Each abstract should be cited by its own year because indicator definitions were occasionally revised. The population series underpins later analysis of the labour force and population development in Syria’s economy.

How to Cite Chapter 2

Cite the chapter as a published government source, not as LevantStats data. A workable reference is: Central Bureau of Statistics (Syria), Statistical Abstract 2009, Chapter 2: Population and Demographic Indicators (Damascus, 2009). If a table number is available, add it after the chapter title. Specify the chapter and indicator so that another researcher can locate the same figure. No stable URL replaced the yearbook, so the printed reference remains the clearest identifier.

Where Official Figures Stop: UN Estimates After 2011

Official figures put Syria’s population indicators on an administrative basis that did not survive the conflict. After 2011, reporting gaps widened, and the Bureau could no longer produce the same national series. UN estimates range beyond those official years.

The UN Population Division’s World Population Prospects 2024 provides modelled population figures for Syria, including the conflict period. The World Bank compiles the same series in its Syria population total indicator, useful for comparing official pre-2011 values with later UN revisions. The UN series is based on demographic modelling and may differ from administrative counts. The yearbook reports registered events, while UN estimates adjust for underreporting and displacement. A citation to Chapter 2 should state the reference year clearly; for any year after 2011, cite the UN estimate rather than the yearbook.

For the economic effects that followed the demographic break, see the discussion of Syria’s later economic crisis.

Background: The 2004 Census Base

The 2004 Syrian census, formally the General Census of Population and Housing 2004, is the reference point behind most population figures in the 2009 abstract. The Bureau used its results to calibrate yearly estimates and to build the age-sex distributions that appear in Chapter 2. Researchers looking for Central Bureau of Statistics Syria population 2009 data should start with the chapter, not with later summaries. For more on the Bureau’s role, see how the Central Bureau of Statistics works. A population indicator cited to 2009 is an update of the 2004 base, adjusted for births, deaths and migration recorded by administrative sources.

Frequently Asked Questions

What does Chapter 2 of Syria’s 2009 Statistical Yearbook contain?

Population and demographic indicators published by the Central Bureau of Statistics through 2009.

Who published Syria’s 2009 population indicators?

The Central Bureau of Statistics (Syria), in the Statistical Abstract 2009, Chapter 2.

Are Syria’s 2009 population indicators reliable after 2011?

They remain valid as official pre-2011 figures; for post-2011 use UN estimates instead.

Where can the 2009 chapter be read?

The official source is the Statistical Abstract 2009, Chapter 2, published by the Central Bureau of Statistics (Syria); it is not hosted elsewhere.

Sources

  • Central Bureau of Statistics (Syria), Statistical Abstract 2009, Chapter 2: Population and Demographic Indicators (Damascus, 2009).
  • UN Population Division, World Population Prospects 2024.
  • World Bank, Syria population total.

Labor is a vital factor in the productivity and development of a society

Since the beginning of history, work has been an essential activity for human life. Human
beings can satisfy their basic needs and develop their potential through work. However, work
has not always been a voluntary activity. For many centuries, forced labor was the norm, and
human beings were enslaved or forced to work in conditions of semi-slavery.

As history progressed, more and more labor rights were established to protect workers from
abuse and exploitation. Today, however, it appears that these rights are becoming
increasingly vulnerable.

Unethical labor practices and disenfranchised industries

Labor exploitation is a form of modern-day slavery, becoming an increasingly severe
problem worldwide. According to estimates by the International Labor Organization (ILO),
around 21 million people are victims of labor slavery worldwide. This means more
people are enslaved today than at any other time in history.

Victims of labor exploitation are often people in vulnerable situations, such as migrants,
homeless people, women, and children. Violence against the LGBT community is also rising,
with gays, lesbians, and transgender people being the most affected and violated.

In many cases, migrants are especially vulnerable to labor exploitation, as they may find
themselves in a foreign country without having the necessary documents to work legally.
This makes them dependent on their employer, which makes them highly vulnerable to
exploitation.

On the other hand, women and children are often victims of sexual exploitation, which is also
a form of modern slavery.

A silent pandemic

According to Unicef estimates, around 2 million children are victims of sexual exploitation
worldwide. This means that more than 5,000 children are victims of this type of exploitation
every year.

Labor and sexual exploitation are just some of the many problems workers face around the
world face. Other common problems include child labor, forced labor, and hazardous and
unhealthy working conditions.

In Europe today, more and more measures are being taken to protect workers’ labor rights.
In particular, efforts are being made to improve the situation of migrants working on the
continent.

For example, in 2018, the Intra-European Workers Directive was adopted, establishing a
legal framework for migrant workers in Europe. The directive aims to encourage the work
and mobility of workers on the continent while protecting their labor rights.
Measures are also being taken to protect children from labor exploitation. In particular,
efforts are being made to eradicate child labor worldwide.

According to the ILO, child labor is a problem that affects 168 million children worldwide.
See the following article.

https://www.ilo.org/global/about-the-ilo/newsroom/news/WCMS_747587/lang–es/index.htm
In 2015, the United Nations General Assembly adopted the 2030 Agenda for Sustainable
Development, which aims to eradicate child labor worldwide. In particular, efforts are being
made to halve the number of working children.
Italy is currently at the forefront of this effort. It has managed to reduce the number of
working children in the country by 80%.
Society has long wanted to protect the family as a fundamental pillar of its development.
However, with time and changing circumstances, this protection has been eroded.

The world demands good working conditions.

Society is constantly changing and developing, and with it, new policies that protect citizens
and families and their traditional values, which means that social welfare must constantly be
evolving to meet the new demands and needs of the environment.

This is why social development has positioned itself as a priority for governments worldwide.
It is an area in constant change and movement where laws and solutions must be
continuously adjusted to ensure the population’s welfare.

Changes in the social sphere directly affect people’s quality of life, and it is, therefore,
essential that they are taken into account to ensure a better future for all.

Sources:

International Year for the Elimination of Child Labour

Child labour rises to 160 million – first increase in two decades

International Labour Organization

The-Central-Bureau-of-Statistics

Everything you need to know about The Central Bureau of Statistics

The Central Bureau of Statistics Syria is responsible for collecting, compiling, and publishing statistical information on the Syrian economy and population. It also plays a key role in the planning and execution of national censuses. The Central Bureau of Statistics Syria was established in 1953.

The mission of the Central Bureau of Statistics Syria is to provide high-quality statistics that meet the needs of users and contribute to the development and improvement of statistical methods and systems. The Central Bureau of Statistics Syria strives to produce timely, reliable, and internationally comparable statistics following international statistical standards. The Central Bureau of Statistics Syria produces a wide range of statistical publications, including annual reports on the Syrian economy, population censuses, and surveys on education, health, and labor.

What is the Central Bureau of Statistics Syria?

The role of the Central Bureau of Statistics Syria in the Syrian economy and population

The Central Bureau of Statistics Syria plays a key role in the Syrian economy by providing accurate and up-to-date statistical information. Government planners and decision-makers use this information to make informed decisions about economic and social policy. The Central Bureau of Statistics Syria also plays a vital role in the population census, which determines the distribution of resources and services. In addition, the Central Bureau of Statistics Syria conducts surveys on topics such as education, health, and labor. These surveys provide valuable insights into the socio-economic conditions of the Syrian people.

The challenges of producing timely, reliable, and internationally comparable statistics

One of the challenges faced by the Central Bureau of Statistics Syria is producing timely, reliable, and internationally comparable statistics. This is a challenge because Syria is a country in transition, and its statistical infrastructure is still being developed. In addition, the Central Bureau of Statistics Syria must adhere to international statistical standards, which can be challenging to implement in a country with limited resources. Another challenge faced by the Central Bureau of Statistics Syria is conducting surveys in a war-torn country like Syria. This is because access to some areas may be restricted, and respondents may be reluctant to participate in surveys due to safety concerns. Despite these challenges, the Central Bureau of Statistics Syria has made great strides in producing high-quality statistics that meet users’ needs.

The importance of high-quality statistics

High-quality statistics are important for the Syrian economy and population. They help government planners and decision-makers make informed economic and social policy decisions. In addition, high-quality statistics are essential for the population census, which determines the distribution of resources and services. Moreover, high-quality statistics are necessary for conducting surveys on topics such as education, health, and labor. These surveys provide valuable insights into the socio-economic conditions of the Syrian people. Finally, high-quality statistics are also important for international comparisons. They allow Syria to benchmark its performance against other countries and identify areas where improvement is needed.

The range of statistical publications produced by the Central Bureau of Statistics Syria

The Central Bureau of Statistics Syria produces a wide range of statistical publications, including annual reports on the Syrian economy, population censuses, and surveys on education, health, and employment. These publications provide valuable information for government planners, decision-makers, businesses, scholars, and the general public. In addition, the Central Bureau of Statistics Syria also produces customized reports upon request.

This website of the Central Bureau of Statistics SyriaThe website of the Central Bureau of Statistics Syria (www.cbssyr.org) is a valuable resource for anyone interested in Syrian statistics. The website provides access to various statistical publications, data sets, maps, and infographics. In addition, the website also features a blog, which provides timely updates on the latest statistics from Syria.


Syria and Lebanon’s currency catastrophe aggravates their economic and social crisis

The causes of the double collapse of the Lebanese (LL) and Syrian (LS) pound are manifold: depletion of revenue sources, multiple and colossal public deficits, absence of governance – even government – endemic corruption and nihilistic politicians, in a context of instability and regional conflicts. Both countries have divergent political and economic systems. Lebanon’s is ultra-liberal, corrupt to the core and, of course, pro-Western. Syria’s is more planned, with a certain liberal twist – and a dose of corruption – over the past decades, before the war unleashed in 2011 destroyed everything in its path.

That ten-year war left deep fractures, impossible to fill without gigantic international aid, which is scarce due to Western financial and economic sanctions. Syria’s rulers – the same autocratic family that has been in power for half a century – reduced hopes for a better life to nothing.

But although Lebanon and Syria have taken different paths, they share many commonalities. Many Lebanese families have Syrian relatives, and vice versa. Several Syrian families contributed to the development in Lebanon of a long thriving banking sector, and dynamic relationships have been woven in the industrial sector. In the early 2000s, some Lebanese banks took stakes or created subsidiaries in Syria, where a timid liberalization of the financial sector was taking shape.

Neither with you nor without you

It should also be recalled that both countries shared the same currency until January 24, 1948, when Lebanon created its own currency after its independence and dissolving any legal relationship with the French Mandatory Power and Syria. In 1950, Syria in turn abolished the customs union between the two countries.

Since October 2019, the Lebanese pound on the official market, which as a guarantee of stability is tied to the dollar (at a rate of 1,507 pounds to the dollar), keeps sinking to abysmal levels on the parallel markets. Its depreciation currently reaches 90%, with an exchange rate on the informal market bordering on 15,000 pounds to the dollar (against 9,800 in July 2020). No one knows when the fall will stop, while the country has been without a government since August, when an explosion in the port of Beirut destroyed an entire neighborhood of the capital and led to the resignation of a government charged with initiating reforms.

“With these insensitive policymakers, we have the feeling of being in contact with a huge boulder or a steel wall,” says Jad Tabet, a civil society figure and secretary general of the Engineers and Architects Syndicate, bitterly. The banks, which were the jewel and engine of the economy before 2018, are on the verge of bankruptcy and prohibit in complete illegality the withdrawal of dollars from bank accounts, except in dribs and drabs and at a disadvantageous rate. In a largely “dollarized” and import-dependent economy, traders suffer, and bankruptcies and unemployment multiply.

In this context, the outgoing Prime Minister, Hassan Diab, warned that the reserves of the Bank of Lebanon (BDL) could not finance all subsidies (wheat, fuel, medicines, medical supplies and foodstuffs) beyond the month of June.

“Living in an illusion”.

Hardship or bankruptcy? The most surprising thing is that the Lebanese banks were swimming in income thanks to deposits from the Lebanese themselves, from expatriates, from the Gulf monarchies and from Syria. For that country, Lebanon was at once a safety valve, a refuge and a place from which industrialists and traders could carry out their operations while benefiting from attractive interest rates until 2019. Everything seemed to be going smoothly before the shipwreck, and the accumulated revenue losses of the Lebanese state and the inability of the monetary authorities to balance the abysmal balance of payments deficit turned out to be the main factor in the crisis. No more foreign currency was coming in, while countries such as Saudi Arabia were reluctant to place their surpluses in the country.

In fact, the BDL encouraged local banks to increase their interest rates to balance the deficits of the public utilities, which were accumulating mountains of debt ($60 billion, or 49 billion euros, in the electricity sector alone). The warnings of experts and international institutions about the situation, which had become unsustainable (the debt-to-GDP ratio had been close to 180% for years), had no effect, since in the short term nothing is more reassuring than blindness.

Thus, a few months after the protests of the northern autumn of 2019 and the draconian measures of the banks, which penalized their depositors by limiting access to their accounts, Prime Minister Hassan Diab announced on March 7, 2020 that for the first time in its history, the country was declaring itself insolvent on a part of its public debt (overdue Eurobonds for $1.2 billion or 999 million euros). It thus sent a very negative signal to the financial markets. “The Lebanese lived in the illusion that everything was fine, while Lebanon was drowning in an ocean of debts,” the prime minister added.

The same month, the Lebanese state declared its insolvency on the whole of its foreign currency debt: $35.8 billion (32 billion euros) on a total debt of $95.5 billion (79 billion euros) by the end of November 2020.

Those who advised more prudence were not listened to. The ship was sinking and panic reigned on board. In July 2020, Alain Bifani, former director general of finance, was claiming that despite tight restrictions and a ban on capital transfers, nearly $6 billion (€5 billion) had fled the country since October 2019

Guilty parties were needed. BDL Governor Riad Salameh and bankers were designated as responsible for a flawed and vicious system that could only endure with unrealistic rates applied to duped customers and in many cases with no other source of income in a near-paralyzed country.

Flattered, then despised

Today, confidence has evaporated. Crowned with glory until yesterday by international financial circles, which attributed to him the highest mark as head of the central bank for his management, Riad Salameh – accused of having implemented a Ponzi scheme, a fraudulent financial construction – is now singled out for his “calamitous” performance, although his mistakes must also be shared by the politicians and the system he helped to build.

The Lebanese judiciary has just opened a preliminary investigation into illegal transfers of funds from the bank’s governor to Switzerland, at the request of the Swiss judiciary. Riad Salameh – who was for a long time the personal business banker of Rafiq Hariri, former Prime Minister and businessman at the time when he worked for the American investment bank Merrill Lynch – denied any professional misconduct.

At the same time, many depositors, considering themselves wronged, initiated legal proceedings against Lebanese banks for their actions and against the BDL, long regarded as an untouchable fortress, a sort of State within the State.

Is there any ray of light in this dark sky where storms follow one after another day after day? “Lebanon is suffering from a severe and prolonged economic depression,” writes the World Bank in a study published in early April, with real GDP in decline for the past three years and inflation reaching 84.3%, while 55% of the population lives below the poverty line according to the United Nations Economic and Social Commission for Western Asia. “Lebanon is threatened by a total and dangerous collapse […], without equivalent to what happened in Greece, Venezuela or Argentina”, warned Lebanese expert Paul Salem, president of the Washington-based Middle East Institute, in an interview with a Lebanese radio station on April 11, while meetings were being held with the IMF, the World Bank and officials of the new U.S. administration. The expert added that the Biden administration had become aware of these dangers and would be ready to act with its partners. “There is an urgent need to prevent a financial and social explosion, in coordination with the IMF. The international community is concerned,” Salem said.

Syria, in a monetary impasse

Would a prospect of an exit from the crisis in Lebanon have positive, albeit limited, effects on Syria? The Syrian pound also falls to its lowest values in history. Paradoxically, the ordeal began with the official end of the fighting, in 2018-2019. Hit by the crisis in Lebanon, the Syrian pound fell in early December 2019 on the black market to 1,000 pounds to the dollar, while the official rate published on the website of the Central Bank of Syria was 434 pounds. Even in the black years of the war, the pound had never fallen to such low levels on the parallel market.

In fact, billions of dollars from Syrian depositors were suddenly blocked by Lebanese banks, generating a shortage of dollars in the Syrian market and causing the Syrian pound to fall. Not to mention the fact that the amount of Syrian deposits placed in Lebanese banks is estimated at several billions of dollars. Bashar al-Assad himself put the figure at $40 billion (33 billion euros), although the real figure is probably much lower.

Be that as it may, at the beginning of April this year, the pound was trading on the informal market at LS 3,700 to the dollar, after hitting a low of LS 4,700 on March 17, i.e. four times less than two years ago. Syrian business circles have become accustomed to the fluctuations of their currency and attribute it to manipulation. Did President Bashar al-Assad not call for the resignation on Tuesday, April 13, at the beginning of Ramadan, of the governor of the Central Bank, Hazem Karful, to calm the waters? “A farce or just another smoke screen?” wondered a shopkeeper in Damascus, while unemployment is rising, the fuel shortage is dragging on and prices are skyrocketing all over the place.

Was the timing right, other observers wondered. Because al-Assad is in the midst of preparing for his re-election, scheduled for May 26. The truth is that the dismissal makes little sense in a devastated country, with a crushed opposition, thousands of prisoners still incarcerated, a covid epidemic that continues to wreak havoc, and attacks and attacks by untamed Islamists who once again attacked the army. And a population in utter despair.

“Yesterday a friend invited me to lunch and the bill came to the amount equivalent to a teacher’s monthly salary,” a Damascus resident who asked to remain anonymous told OrientXXI. At least some can eat, even if at an exorbitant price. Because a few hundred kilometers from the capital, in an apocalyptic landscape, some 2.8 million displaced Syrians from the war huddle in makeshift camps in Idlib province, in the northwest of the country, a once prosperous and agricultural region now under the control of a jihadist group.

“Our air is different from theirs.”

Controversy erupted on March 24 after a surprise visit to Damascus by Lebanese Health Minister Hamad Hasan. Syria gave the go-ahead to deliver 75 tons of oxygen to Lebanese hospitals, particularly for covid-19 patients, due to shortages in Lebanese factories.

“Despite the increased need for oxygen to treat Syrian patients, the response was positive […]. Relying on brother and friend [Bashar al-Assad] in times of crisis is a winning bet,” said Hassan, a minister of the Shiite Hezbollah movement in the outgoing Lebanese government.

The amount of oxygen available in Lebanon is barely enough for a single day, while intensive care units are almost saturated, with a thousand patients on ventilators, the minister said. There are two factories producing oxygen in Lebanon, and the vice-president of one of the country’s largest factories, Khaled Hadla, said that local production was insufficient and that his country imported part of its needs from Syria before Damascus limited its exports to supply its own market.

Farès Souhaid, a former Lebanese deputy on the anti-Syrian side, reacted in a tweet addressed to the Syrian president: “We don’t want your oxygen… Our air is different from yours”. The reaction inflamed the social networks, as the issue revives the deep divergences in Lebanon on the relevance or not of a normalization of relations with Syria, longed for by one part of the Lebanese and rejected by the other.

Since the beginning of the pandemic, 455,381 cases of covid-19 and 6,013 deaths have been officially recorded in Lebanon. In Syria, the governmental areas – approximately two thirds of the territory – recorded 17,743 cases and just over a thousand deaths, but in reality the balance would be much higher than the official figures.

Memories of Syria from a 113 year-old refugee

Hamde Fares’ gnarled fingers nimbly run the beads of the masbaha, the Muslim rosary, which she holds in her left hand. Every so often, the elderly Syrian woman pauses in her story to murmur a prayer. According to her Syrian ID card, she is 113 years old, so theoretically she was 105 when she fled the war in Syria to become a refugee. Sitting on a mattress inside the tent she inhabits in the informal camp of Tueli, in northeastern Lebanon and bordering the Syrian border, this herdswoman recounts the last decade of strife in Syria, the era of greatest poverty in more than a century of life, she says. Wiry, the woman clears her throat, her throat dry from not drinking water all day. Despite her age, she still observes the fast in this holy month of Ramadan.

Fares crossed the Lebanese border in 2013 accompanied by her youngest son, Rasein, who today sits next to her and is in charge of shouting questions in her ear, without a mask. “She never studied, she is a simple and devout woman,” the son apologizes to each answer. She lost her sight in 2001, just as the ophthalmologist Bashar el-Assad was one year in power after the death of his father, Hafez el-Assad. The United Nations counts 865,000 Syrians living as refugees in Lebanon, a figure the Lebanese government puts at 1.5 million. Of these, only 50 are over 100 years old, says Lisa Abou Khaled, spokeswoman for the Refugee Agency (UNHCR). Fares is the oldest among those registered, after another 119-year-old compatriot who “neither sees nor hears,” says Abou Khaled.

The old woman is hard of hearing, but her memory is intact. “Before, there were no borders, I took my cattle from one side to the other without any problems,” she recalls in an interview last April 22. By “before,” he means at the beginning of the last century. In winter he would walk for weeks to take his camels and cows to graze in Al Badia, the Syrian desert in the center of the country. In summer he did so in the province of Homs and in the meadows of the Lebanese Bekaa Valley, long before France and the United Kingdom agreed in 1916 to partition the Middle East into zones of direct control and influence. A line then separated the land where Fares’ animals grazed, dividing Lebanon and Syria on either side. Then, the Bedouin and her family stopped being nomads to settle in their village in Homs.

Her family is from Nahariyah, a small village on the outskirts of the city of Qusseir (Syria), although Fares probably came into the world in the winter of 1908, because her identity card marks Al Badia as her place of birth that year. It was precisely there that he was surprised by the departure of the French troops when in 1946 Syria ceased to be a Gallic mandate to become an independent country. “When we returned from Al Badia to the village there was not a Frenchman left,” he recalls. For the Bedouins, identity did not depend then on a document issued in Damascus but on the tattoos that still mark the tanned skin of this woman between her eyebrows and chin, symbols of belonging to the Nughim tribe. Official registration came later.

At 113 years old, Hamde Fares is one of the longest-lived Syrian refugees in Lebanon. Another 50 displaced persons, among more than 865,000 refugees, have lived more than a century.Natalia Sancha García

For this woman the history of Syria is also not defined by political preferences or social freedoms that guide the debates of her grandchildren, but by droughts, taxes, confiscations of livestock and obstacles in the movement to graze. In the time of the French, he asserts, they were the only ones with vehicles. “Times have changed,” the old woman continues, “because now the ranchers transport their animals in trucks.”

The departure of the French ushered in an era of political and economic instability, Fares continues. For her, Maamoun’s arrival in Kuzbari in 1952 as vice president brought an improvement in the quality of life. None of those present in the store, between the two sons and several of the more than 100 grandchildren and great-grandchildren, know who Kuzbari is. The younger ones scramble for a cell phone to Google the name. However, when asked what she thinks of the Islamic State’s (ISIS) entry into the war, the old woman replies, “Who are those?”, sparking laughter from those present.

Of the five children she gave birth to, two died of natural causes. Her husband has been dead for more than half a century. The rest are all refugees in various camps in Lebanon. Qusseir was one of the toughest battles of the war and the town is now taken over by Lebanese Hezbollah militiamen. Return is impossible. Of the 3,000 inhabitants of the village, only about 30 have remained in their homes. The rest have scattered to seek refuge in neighboring countries or in Europe, says his son Rasein.

Political instability was a constant in the Levantine country, recalls the centenarian: “The leaders did not even last six months”. This is how she sums up the era between 1949 and 1970, when eight coups d’état took place. The last one brought Hafez el Asad to power, establishing a period of stability based on an iron fist. “At the beginning everything went very well with Hafez, and life improved. We had access to hospitals and the young people were educated,” says the refugee. “Then came the fear,” she continues. She voted for the president by signing each ballot “with her thumb smeared in ink”. Hafez won four consecutive elections with between 99.9 and 100% of the votes. Fares will not vote on May 25, when Bashar is expected to win his fourth election as president in a country devastated by a decade of war, economically ruined and plunged into pandemic.

Clinging to her masbaha, Fares claims she does not fear covid-19. In fact, she has refused to be vaccinated. “I have delicate skin and fear a skin reaction,” she says. The last 10 years of strife are just one passage in this woman’s memory, but the saddest, she says: “Before there was always something to eat, now Syrians go hungry.” Blindness prevented her from seeing anything of what was happening, but she was able to hear the roar of the bombs and live in her flesh the hardship of becoming a refugee dependent on UN aid in a land now alien to her, where her children, opposed to the regime, took her. The same land where she used to graze her cattle.

She says she is fortunate because, although she no longer has animals or land, she lives surrounded by her family, even if it is crammed into a tent. Blindness has condemned her to spend her days lying on a mattress. Dressed in black and with her head covered by a cloak, she agrees to get up and walk a few steps to pose for the camera. She does it slowly but without much help as she tells how much she misses the apricots, figs and pistachios of her village. A village to which, “if Allah wills it,” he may one day return.

Norway, the sleeping green giant

As one of the world’s leading exporters of natural gas, Norway faces a unique challenge in a world increasingly moving away from fossil fuels. The country has all the financial, technological and human resources it needs to thrive in a decarbonized future; what is lacking is political leadership.

LONDON – Responding to the climate emergency is difficult for everyone, but particularly for countries whose economies depend on oil extraction or production. Decarbonization is an opportunity to kick-start a green industrial revolution, but as more and more nations join this path to future prosperity, assets, technologies and capabilities that rely on fossil fuels will lose value, and that will put employment, exports and industrial innovation in oil-dominated economies at risk.

One such economy, Norway (the world’s third largest exporter of natural gas) today faces a unique challenge. Its industrial and investment structure is closely tied to hydrocarbon-based sectors and services (which in 2019 generated 36% of total exports), but the energy it consumes comes almost entirely from renewable sources (water energy conversion).

So perhaps the Norwegian economy is now ready for a green industrial transition, with the caveat that falling global demand for fossil fuels will lock in its main growth engine.

Norway’s dependence on hydrocarbons is a symptom of “Dutch disease”: the problem that occurs when one dominant sector thrives to the detriment of the others. The huge disparity in hydrocarbon investment compared to other industries attracts the most skilled professionals to the fossil fuel sector. At the same time, the extraordinary profitability of the oil and gas sector has generated excessive price and wage growth in the rest of the economy, creating difficulties for other exporters.

This is why Norway has been one of the OECD countries that since the late 1990s has lost the most international market share in the non-energy export sectors. During the last decade, Norway’s non-oil trade deficit has grown steadily and the share of the manufacturing sector in the economy has halved compared to the other Nordic countries.

To make matters worse, a recent report by the Norwegian Central Bureau of Statistics predicts that over the next decade, investment in the Norwegian energy sector will decline. While average annual investment in the sector over the previous decade exceeded NOK 170 billion (about $20 billion), between 2025 and 2034 that figure is projected to decline by about NOK 60 billion (even without oil production curtailment policies).

It is clear that Norway needs a new industrial strategy. In a recent report, we propose a way to use the technical and financial resources of the oil sector to turn Norway into a “green giant.” But the transition from oil extraction to a greener economy will not be automatic: it demands bold, but very well calibrated, action from the public sector. Government cannot micromanage the process, because it would stifle innovation, but neither can it leave it entirely to the market.

The solution is for governments to show the way with high-risk investments in the early stages, which will then be joined by private actors, with rewards for those willing to invest and innovate. In the case of Norway, an industrial strategy is needed that directs the state’s considerable financial resources towards investments in the creation of a new industrial base focused on green energy.

Norway has the world’s largest sovereign pension fund, but has not yet channeled its resources into investments in the green transition, inside or outside the country. On the contrary, Norway’s Statens Pensjonsfond Utland (SPU) is a major financier of some of the most devastating fossil fuel projects in the planning or development phase today. A recent report warns that just twelve of these projects will consume three-quarters of what remains of the world’s carbon budget, making it extremely difficult to limit global warming to 1.5 °C.

Under current Norwegian tax regulations, SPU deposits oil revenues in a fund earmarked for overseas investment. Every year Norway transfers an average of 3% of the value of the fund to the domestic economy, a sustainable withdrawal rate as it matches the expected return on the fund.

This policy has proved effective in limiting inflationary pressure from oil extraction, while providing an additional source of revenue to the state. But today Norway needs a patient and lasting financing process that makes economic diversification possible. As the current fiscal rules allow large public investments to be maintained outside the normal state budget, it is aggravating the Dutch disease by perpetuating a path dependency on oil.

But it does not have to be this way. It is possible to turn the SPU into a powerful investor with a sense of mission and presence at home and abroad. Instead of using oil revenues to recapitalize the fund, they can be directed to a new public green investment bank, acting in coordination with other public funds and agencies dedicated to the green transition.

The Norwegian national innovation system is characterized by significant state involvement. In particular, the Norwegian state owns 67% of the Norwegian oil industry’s flagship company, Equinor (formerly Statoil). But the Norwegian state-owned companies that were once key players in creating, out of nothing, the oil industrial ecosystem, have not played the same role in the green transition. Instead of reinvesting its profits in renewable energy sources, in 2019 Equinor announced that between now and 2022 it will spend $5 billion on buying back its own shares.

The impact of Covid-19 highlighted the risks of over-reliance on (volatile) energy markets. While the Danish energy giant Ørsted got through the pandemic without major inconvenience and did not halt the process of transition to renewable sources that it started a decade ago, Equinor had to cut dividends and take on debt to maintain its commitments to shareholders in a context of insufficient revenues.

Like its Danish counterpart, Equinor must become an energy giant with a sense of mission. This requires freeing its managers from the pressure to distribute dividends, returning it to the status of a fully state-owned company focused on the country’s economic future.

Mariana Mazzucato, Professor of Economics of Innovation and Public Value at University College London, is founding director of the UCL Institute for Innovation and Public Purposes. She is the author of The Value of Everything: Making and Taking in the Global Economy, The Entrepreneurial State: Debunking Public vs Private Sector Myths and, most recently, Mission Economy: A Moonshot Guide to Changing Capitalism.